ATTENTION: For Those who are serious about Getting Pre-Qualified FAST!
Bill Rapp, Mortgage Originator: NMLS 228246
"Brokers Are Better.
Better Pricing, Better Service!"
Subscribe To My List Below To Get Your Mortgage Quote Now!
Simply enter your name and email below:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
FHA 203 H Loan Product
The Section 203(h) program allows the Federal Housing Administration (FHA) to insure mortgages made by qualified lenders to victims of a major disaster who have lost their homes and are in the process of rebuilding or buying another home.
Purpose:
Through Section 203(h), the Federal Government helps victims in Presidentially designated disaster areas recover by making it easier for them to get mortgages and become homeowners or re-establish themselves as homeowners.
Type of Assistance:
This program provides mortgage insurance to protect lenders against the risk of default on mortgages to qualified disaster victims. Individuals are eligible for this program if their homes are located in an area that was designated by the President as a disaster area and if their homes were destroyed or damaged to such an extent that reconstruction or replacement is necessary. Insured mortgages may be used to finance the purchase or reconstruction of a one-family home that will be the principal residence of the homeowner. Like the basic FHA mortgage insurance program it resembles (Section 203(b) Mortgage Insurance for One to Four Family Homes), Section 203(h) offers features that make recovery from a disaster easier for homeowners:
No down payment is required. The borrower is eligible for 100 percent financing. Closing costs and prepaid expenses must be paid by the borrower in cash or paid through premium pricing or by the seller, subject to a 6 percent limitation on seller concessions.
FHA mortgage insurance is not free. Mortgagees collect from the borrowers an up-front insurance premium (which may be financed) at the time of purchase, as well as monthly premiums that are not financed, but instead are added to the regular mortgage payment.
HUD sets limits on the amount that may be insured. To make sure that its programs serve low and moderate income people, FHA sets limits on the dollar value of the mortgage. The current FHA mortgage limit can be viewed online. These figures vary over time and by place, depending on the cost of living and other factors (higher limits also exist for two to four family properties).
Eligible Customers:
Anyone whose home has been destroyed or severely damaged in a Presidentially declared disaster area is eligible to apply for mortgage insurance under this program.
Application:
The borrower's application for mortgage insurance must be submitted to the lender within one year of the President's declaration of the disaster. Applications are made through an FHA approved lending institution, who make their requests through a provision known as "Direct Endorsement," which authorizes them to consider applications without submitting paperwork to HUD. Mortgage insurance processing and administration for this and other FHA single family mortgage insurance products are handled through HUD's Homeownership Centers.
My best advice to you is to call Bill Rapp, the Mortgage Viking, to discuss your options today 281-222-0433.
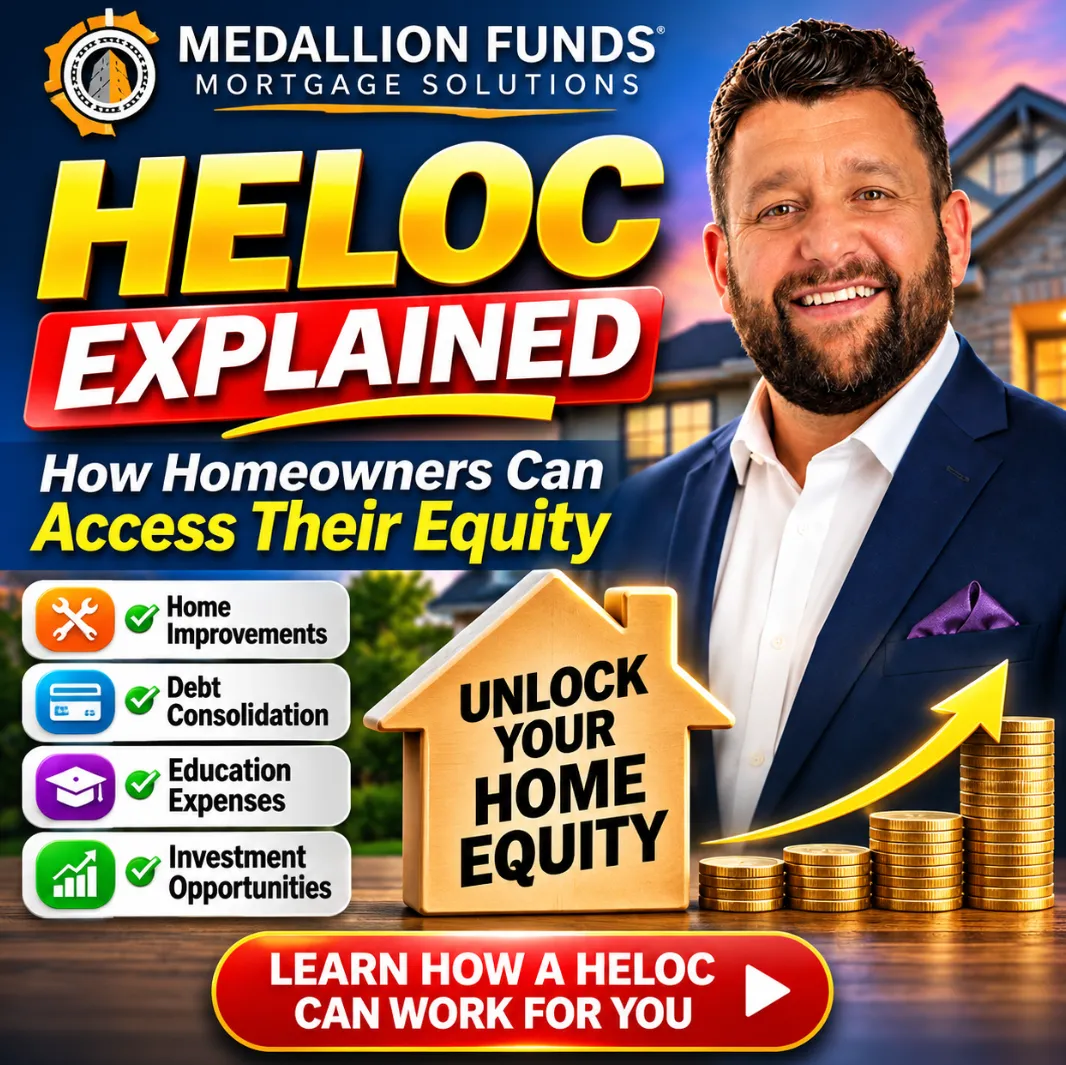
🏡 HELOC Explained: How to Access Home Equity 💰
🏡 HELOC Explained: How to Access Home Equity 💰
💵 HELOC Loans: Unlock Your Home Equity 🏠
_______________________________________________________________________________
🏡 HELOC Explained: How Homeowners Can Access Their Equity
Your home could be one of your most valuable financial assets. But did you know you may be able to access some of its equity without selling your property or refinancing your existing mortgage?
A Home Equity Line of Credit (HELOC) allows qualified homeowners to borrow against their available home equity while generally keeping their existing first mortgage in place.
Whether you're planning home renovations, consolidating higher-interest debt, covering major expenses, or exploring investment opportunities, understanding how a HELOC works can help you make informed financial decisions.
I'm Bill Rapp, CCIM, with Medallion Funds. In this guide, I'll explain how HELOC loans work, how much you might qualify to borrow, the advantages and risks, and when a HELOC might make sense compared with other mortgage financing options.
What Is a HELOC?
A HELOC, or Home Equity Line of Credit, is a revolving credit line secured by your home.
Unlike a traditional mortgage or home equity loan, which generally provides funds in a lump sum, a HELOC allows you to borrow money as needed, up to an approved credit limit.
Think of it as a credit card backed by your home's equity, although its terms, collateral, and repayment obligations are significantly different.
For example, if you're approved for a $75,000 HELOC, you might initially withdraw $20,000 for kitchen renovations and access additional funds later, subject to your remaining credit availability and the lender's terms.
You generally pay interest only on the outstanding amount you borrow, not your entire approved credit limit.
Most HELOCs have variable interest rates, meaning your payments may change as market rates move.
How Does a HELOC Work?
A typical HELOC has two phases.
Phase 1: The Draw Period
The draw period commonly lasts five to ten years, although terms vary by lender.
During this time, you can:
·Borrow against your approved credit line.
·Repay borrowed principal.
·Access available funds again, subject to the credit agreement.
·Potentially make interest-only minimum payments.
Some HELOC programs also offer fixed-rate conversion features for certain balances.
Phase 2: The Repayment Period
After the draw period ends, the repayment period begins.
At this stage, you generally can no longer withdraw additional funds, and your required payments include both principal and interest.
Depending on the loan agreement, repayment may extend over ten to twenty years, or a balloon payment may become due.
Important: Your monthly payment could increase substantially when your HELOC transitions from interest-only payments to principal-and-interest payments.
Understanding this payment adjustment before borrowing is essential.
How Much Home Equity Can You Borrow?
Your available borrowing capacity depends on your home's appraised value, outstanding mortgage balances, lender guidelines, creditworthiness, and debt-to-income ratio.
One of the most important measurements is your combined loan-to-value ratio (CLTV).
CLTV compares the total debt secured by your property with its value.
HELOC Calculation Example
Let's assume:
Item | Amount |
Current home value | $500,000 |
Existing mortgage balance | $300,000 |
Current home equity | $200,000 |
Hypothetical maximum CLTV | 85% |
Maximum combined mortgage debt | $425,000 |
Potential HELOC credit limit | $125,000 |
Calculation:
$500,000 × 85% = $425,000
$425,000 − $300,000 = $125,000
In this example, the homeowner could potentially qualify for a HELOC of up to $125,000, assuming the lender permits 85% CLTV and the borrower meets all underwriting requirements.
Some lenders permit higher or lower CLTV limits depending on the property, credit profile, occupancy, and program.
The maximum calculated equity is not a guaranteed loan approval.
Five Popular Ways Homeowners Use a HELOC
1. Home Improvements and Renovations
One of the most common uses of a HELOC is financing home improvements.
Projects may include kitchen remodeling, bathroom upgrades, roof replacement, outdoor living spaces, or major repairs.
Because renovation expenses often occur in stages, a HELOC may provide greater flexibility than receiving all borrowed funds at once.
However, improvements do not necessarily increase property value by the amount spent.
2. Debt Consolidation
Homeowners sometimes use a HELOC to consolidate higher-interest credit card balances or personal loans.
For example, replacing a credit card balance with a lower-rate HELOC could reduce interest expenses.
But there is a critical tradeoff.
A HELOC converts previously unsecured debt into debt secured by your home.
If you cannot make the payments, your property could be at risk of foreclosure.
Debt consolidation also becomes less effective if you accumulate new credit card balances after paying off the old ones.
3. Education and Major Family Expenses
A HELOC may provide funds for tuition, educational expenses, or other substantial financial obligations.
However, homeowners should compare federal student loan protections, unsecured financing alternatives, and the consequences of pledging their home as collateral.
4. Real Estate Investment Opportunities
Some homeowners use home equity as a source of funds for an investment property down payment, renovations, or acquisition expenses.
This approach introduces additional leverage and risk.
Investment property cash flow, vacancy, financing costs, and the borrower's ability to repay should be evaluated carefully.
Borrowing against your primary residence to fund an investment means your home may be exposed to losses associated with that investment.
5. Emergency Liquidity
An available HELOC may serve as a supplemental source of liquidity for unexpected expenses.
However, lenders can freeze or reduce credit lines under certain circumstances, and HELOC access should not replace an adequately funded emergency reserve.
HELOC vs. Home Equity Loan vs. Cash-Out Refinance
These three financing options allow homeowners to access equity, but they work differently.
Feature | HELOC | Home Equity Loan | Cash-Out Refinance |
Funds received | As needed | Lump sum | Lump sum |
Rate structure | Usually variable | Usually fixed | Fixed or adjustable |
Existing first mortgage | Generally stays | Generally stays | Replaced |
Repayment | Draw and repayment phases | Scheduled installments | New mortgage term |
Best suited for | Staged or uncertain expenses | Known one-time expense | Replacing first mortgage while accessing equity |
Why Keeping Your Existing Mortgage Matters
Suppose you currently have a first mortgage with a 3.25% interest rate.
Refinancing your entire mortgage balance into a new loan at a substantially higher rate could increase your borrowing costs.
A HELOC may allow you to preserve the existing first mortgage while accessing additional equity through a separate credit line.
However, the HELOC rate, combined payments, closing costs, and long-term interest expenses must still be evaluated.
The best mortgage financing decision is not always the one with the lowest advertised interest rate.
What Are Typical HELOC Requirements?
Lenders evaluate several factors when determining eligibility.
Credit score: Many programs favor borrowers with credit scores around 680 or higher, although some programs accept lower scores and others require stronger credit.
Home equity: Lenders commonly limit total secured borrowing to a specified CLTV, often around 80%–85%, with variations by program.
Debt-to-income ratio: Lenders review existing monthly debt obligations against qualifying income.
Income documentation: W-2 employees may provide pay stubs and tax documents, while self-employed borrowers may need additional business or alternative income documentation.
Property eligibility: Requirements vary for primary residences, second homes, investment properties, condominiums, and other property types.
Property valuation: An appraisal, automated valuation, or another acceptable valuation method may be required.
These are illustrative guidelines, not universal approval standards.
How Are HELOC Interest Rates Determined?
Most HELOCs have variable rates tied to a benchmark such as the U.S. prime rate.
A typical pricing structure is:
HELOC interest rate = Prime rate + or − lender margin
For example, if the prime rate were hypothetically 7.00% and the lender margin were +0.50%, the resulting variable HELOC rate would be 7.50%.
That is an illustration, not a current rate quote.
Your actual pricing may depend on credit score, CLTV, line size, property occupancy, lender guidelines, and promotional terms.
Some HELOCs also include annual fees, transaction fees, early closure fees, or minimum draw requirements.
Always review the complete credit agreement.
Real-World Example: Using a HELOC for a $50,000 Renovation
Imagine a homeowner with substantial equity who wants to renovate a kitchen and bathrooms.
Rather than refinance the entire first mortgage, the homeowner obtains a $75,000 HELOC and draws $50,000.
Assume a hypothetical 8.00% variable annual interest rate.
During an interest-only draw period, the approximate monthly interest payment on that $50,000 balance would be:
$50,000 × 8.00% ÷ 12 = $333.33 per month
That payment does not reduce principal.
If the same $50,000 balance were amortized over 15 years at an unchanged 8.00% rate, the principal-and-interest payment would be approximately $477.83 per month.
This illustrates why homeowners need to understand both the draw-period and repayment-period obligations.
Actual payments depend on the lender's terms, balance, rate changes, fees, and repayment structure.
Are HELOC Interest Payments Tax-Deductible?
HELOC interest may be deductible under applicable federal tax rules when borrowed funds are used to buy, build, or substantially improve the qualified home securing the loan, subject to applicable limitations.
Using HELOC proceeds for personal expenses, credit card consolidation, or unrelated investments does not automatically qualify for the home mortgage interest deduction.
Tax treatment depends on the use of proceeds, current law, and individual circumstances.
Consult a qualified tax advisor before relying on any potential deduction.
What Are the Biggest Risks of a HELOC?
A HELOC can be a useful financial tool, but homeowners should consider these risks:
·Variable interest rates: Rising rates can increase borrowing costs and monthly payments.
·Payment shock: Payments may rise when the repayment period begins.
·Foreclosure exposure: Your home secures the debt.
·Declining property values: Reduced home equity may affect future refinancing flexibility.
·Credit line restrictions: A lender may suspend or reduce borrowing availability under permitted circumstances.
·Overborrowing: Easy access to credit can encourage unnecessary spending.
Before opening a HELOC, calculate whether your household could afford payments if interest rates increased or your income declined.
Is a HELOC Better Than Refinancing?
The answer depends on your existing mortgage, financial goals, and borrowing needs.
A HELOC may be worth exploring when you have a favorable first-mortgage rate, want to borrow funds gradually, or need flexibility.
A home equity loan may be preferable when you need a specific lump sum and want predictable fixed payments.
A cash-out refinance may be more appropriate when replacing your existing mortgage also improves your overall financing structure.
Comparing the total borrowing costs of all available options is the best approach.
How to Apply for a HELOC
A typical HELOC application involves:
1.Estimating your home's value and existing mortgage balance.
2.Reviewing your credit profile and qualifying income.
3.Comparing available lender programs.
4.Determining your preferred credit limit.
5.Completing property valuation and underwriting.
6.Reviewing disclosures, closing costs, and repayment terms.
7.Closing the loan and accessing funds according to your agreement.
Working with a mortgage broker can help you compare available financing structures rather than relying on a single lender's offering.
Final Thoughts: Make Your Home Equity Work Strategically
Your home equity represents a valuable financial resource, but accessing it should be part of a well-considered financial plan.
A HELOC can offer flexibility for renovations, major expenses, and other qualified borrowing needs while allowing you to retain your existing first mortgage.
The key is understanding the interest rate, repayment obligations, total borrowing cost, and risks before proceeding.
I'm Bill Rapp, CCIM, with Medallion Funds.
If you're considering a HELOC, home equity loan, or cash-out refinance, I'd be happy to help you explore available mortgage options and determine which structure best aligns with your goals.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
📞 Call or Text: 281-222-0433
🌐 Website: https://billrapponline.com
🎥 Subscribe to Mortgage Viking: https://www.youtube.com/@billrapp-medallion-funds
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302Las Vegas, NV 89141
Texas Complaint and Recovery Fund Notice
All Rights Reserved Copyright © 2021 - Bill Rapp The Mortgage Viking | NMLS #228246