ATTENTION: For Those who are serious about Getting Pre-Qualified FAST!
Bill Rapp, Mortgage Originator: NMLS 228246
"Brokers Are Better.
Better Pricing, Better Service!"
Subscribe To My List Below To Get Your Mortgage Quote Now!
Simply enter your name and email below:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
FHA 203 H Loan Product
The Section 203(h) program allows the Federal Housing Administration (FHA) to insure mortgages made by qualified lenders to victims of a major disaster who have lost their homes and are in the process of rebuilding or buying another home.
Purpose:
Through Section 203(h), the Federal Government helps victims in Presidentially designated disaster areas recover by making it easier for them to get mortgages and become homeowners or re-establish themselves as homeowners.
Type of Assistance:
This program provides mortgage insurance to protect lenders against the risk of default on mortgages to qualified disaster victims. Individuals are eligible for this program if their homes are located in an area that was designated by the President as a disaster area and if their homes were destroyed or damaged to such an extent that reconstruction or replacement is necessary. Insured mortgages may be used to finance the purchase or reconstruction of a one-family home that will be the principal residence of the homeowner. Like the basic FHA mortgage insurance program it resembles (Section 203(b) Mortgage Insurance for One to Four Family Homes), Section 203(h) offers features that make recovery from a disaster easier for homeowners:
No down payment is required. The borrower is eligible for 100 percent financing. Closing costs and prepaid expenses must be paid by the borrower in cash or paid through premium pricing or by the seller, subject to a 6 percent limitation on seller concessions.
FHA mortgage insurance is not free. Mortgagees collect from the borrowers an up-front insurance premium (which may be financed) at the time of purchase, as well as monthly premiums that are not financed, but instead are added to the regular mortgage payment.
HUD sets limits on the amount that may be insured. To make sure that its programs serve low and moderate income people, FHA sets limits on the dollar value of the mortgage. The current FHA mortgage limit can be viewed online. These figures vary over time and by place, depending on the cost of living and other factors (higher limits also exist for two to four family properties).
Eligible Customers:
Anyone whose home has been destroyed or severely damaged in a Presidentially declared disaster area is eligible to apply for mortgage insurance under this program.
Application:
The borrower's application for mortgage insurance must be submitted to the lender within one year of the President's declaration of the disaster. Applications are made through an FHA approved lending institution, who make their requests through a provision known as "Direct Endorsement," which authorizes them to consider applications without submitting paperwork to HUD. Mortgage insurance processing and administration for this and other FHA single family mortgage insurance products are handled through HUD's Homeownership Centers.
My best advice to you is to call Bill Rapp, the Mortgage Viking, to discuss your options today 281-222-0433.
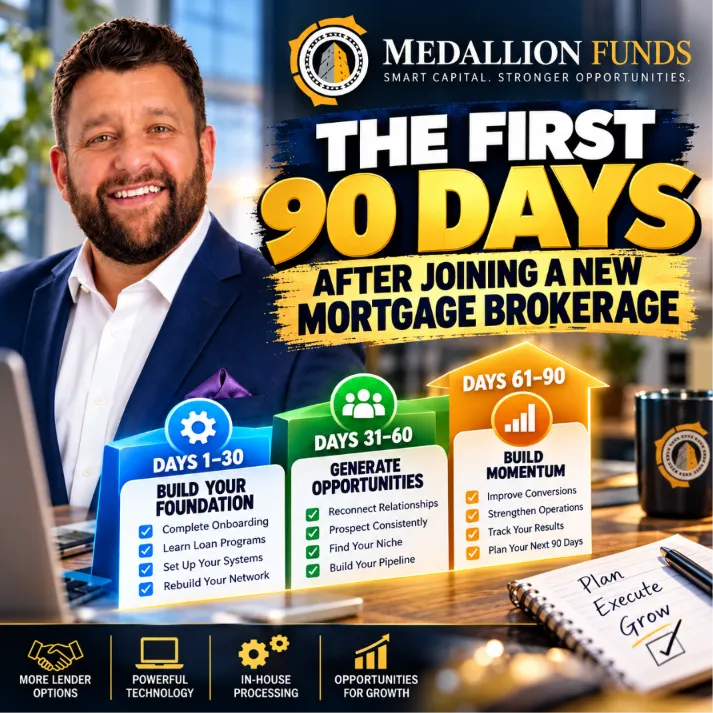
🚀 The First 90 Days at a New Mortgage Brokerage: Your Roadmap to Success 🏆
🚀 The First 90 Days at a New Mortgage Brokerage: Your Roadmap to Success 🏆
💼 Changing Mortgage Companies? 10 Steps to Build a Stronger Pipeline in Your First 90 Days 📈
________________________________________________________________________________
🚀 The First 90 Days at a New Mortgage Brokerage: Your Roadmap to Success
Changing mortgage companies can be one of the most important career decisions a loan officer makes.
Whether you're transitioning from a retail bank, leaving a correspondent lender, or joining a mortgage brokerage for the first time, your first 90 days can establish the foundation for your long-term success.
But here's something many mortgage professionals overlook:
Changing companies doesn't automatically change your production. Changing your strategy, systems, relationships, and execution does.
A new mortgage brokerage may offer access to more lenders, competitive loan programs, stronger technology, and greater flexibility. However, those advantages only create value when you know how to use them.
At Medallion Funds, we believe successful loan officers need more than a place to hang their license. They need the right tools, lender relationships, operational support, and a business development strategy designed for sustainable growth.
Here's a practical 90-day roadmap for making your transition successful.
Days 1–30: Build Your Foundation
Your first month should focus on understanding your new brokerage, learning its capabilities, and preparing your business for growth.
1. Complete Your Licensing and Compliance Transition
Before originating loans under your new brokerage, confirm that all required licensing, sponsorship, and regulatory requirements have been satisfied.
Your transition checklist should include:
·Confirming applicable NMLS sponsorship and state licensing requirements.
·Completing required onboarding and compliance training.
·Understanding advertising and marketing approval procedures.
·Reviewing company policies for borrower communication, disclosures, and data security.
·Establishing your business email, technology access, and document management systems.
Important: Never assume that joining a new company automatically authorizes you to originate loans. State licensing and sponsorship requirements must be satisfied before conducting regulated activities.
2. Learn Your New Mortgage Product Menu
One of the biggest potential advantages of joining a mortgage brokerage is gaining access to financing options beyond a single institution's products.
Depending on your brokerage's lender relationships, these may include:
Traditional residential mortgages
·Conventional loans
·FHA financing
·VA home loans
·USDA mortgages
·Jumbo financing
Specialty residential financing
·Doctor and dentist mortgage programs
·Bank statement loans
·Non-QM mortgages
·DSCR investment property loans
·Asset-utilization mortgages
·Bridge financing
Commercial financing opportunities
·SBA 7(a) and 504 financing
·Commercial investment property loans
·Multifamily mortgages
·Owner-occupied commercial financing
·Construction and development financing
Understanding these products can help you identify borrowers who may not fit conventional underwriting requirements.
Your goal during the first 30 days: Become proficient in identifying which loan programs fit which borrower scenarios.
3. Master Your Technology and Loan Origination Systems
Technology should improve your productivity—not become another obstacle.
Learn how to use your brokerage's:
·Customer relationship management (CRM) platform
·Loan origination system (LOS)
·Pricing and lender comparison tools
·Document collection and borrower portals
·Marketing automation capabilities
·Pipeline tracking and reporting
At Medallion Funds, our platform emphasizes technology, processing support, and access to a broad range of lending solutions.
For commercial opportunities, our relationship with the CommLoan Empower Program provides access to its CUPID™ commercial lending marketplace and a network of 700-plus lenders.
That expanded capability can help loan officers recognize opportunities beyond traditional residential mortgages, subject to licensing, program eligibility, and company procedures.
4. Communicate Your Transition to Your Professional Network
Your existing relationships may be among your most valuable business assets.
Develop a compliant communication strategy for:
·Real estate agents
·Builders
·Past clients
·Financial advisors
·CPAs
·Attorneys
·Business owners
·Commercial real estate professionals
Explain why you made the transition and, more importantly, how your expanded capabilities may benefit the people you serve.
Avoid making your announcement solely about compensation or your new company's name.
Instead, focus on the additional solutions and service you can provide.
30-Day Milestone: Complete onboarding, understand your lending platform, and establish a clear business development plan.
Days 31–60: Rebuild Relationships and Generate Opportunities
Once your systems are operational, the next priority is production activity.
5. Reconnect With Your Referral Partners
Successful mortgage originators rarely build sustainable businesses through occasional prospecting.
Consistent relationships drive opportunities.
Schedule conversations with your strongest referral partners and ask:
·What financing challenges are your clients experiencing?
·Which types of transactions are becoming more difficult to finance?
·Are you working with self-employed buyers or real estate investors?
·Do you have clients who may benefit from specialty loan programs?
·How can I make your transactions easier to manage?
The objective is to become a trusted financing resource—not simply another loan officer requesting referrals.
6. Develop Two or Three Specialized Lending Niches
Trying to market every mortgage product to everyone can dilute your message.
Instead, identify borrower segments that align with your expertise and local market.
Doctors and dentists: Specialty financing may help qualified healthcare professionals purchase homes while managing student loan obligations and preserving liquidity.
Self-employed borrowers: Bank statement and other Non-QM programs may offer alternative qualification approaches for borrowers with complex income documentation.
Real estate investors: DSCR loans and portfolio financing may provide solutions for qualifying rental property investments.
Veterans and military families: VA lending offers important benefits for eligible borrowers, including potentially no down payment and no monthly mortgage insurance.
Business owners: Commercial and SBA financing can create opportunities to help qualified borrowers purchase owner-occupied business real estate.
At Medallion Funds, we believe specialization can differentiate loan officers in a crowded mortgage market.
7. Establish a Consistent Marketing Strategy
Your marketing should reinforce your expertise and generate conversations.
Consider a weekly schedule that includes:
·Educational social media posts
·Short-form mortgage videos
·Referral partner outreach
·Mortgage program explainers
·Local networking
·Client follow-up
·Email newsletters
For example, a loan officer specializing in real estate investors could produce content explaining DSCR loans, blanket mortgages, cash-out refinancing, and rental property financing.
A loan officer targeting medical professionals might focus on physician mortgage programs, student debt considerations, and financing for practice owners.
60-Day Milestone: Establish a repeatable prospecting routine, reconnect with referral sources, and develop a measurable pipeline of qualified opportunities.
Days 61–90: Build Momentum and Optimize Your Business
By your third month, the focus should shift from learning the platform to improving your execution.
8. Evaluate Your Mortgage Pipeline
A healthy mortgage business requires more than a list of leads.
Review the performance of each stage:
1.New prospect inquiries
2.Initial borrower consultations
3.Applications received
4.Pre-approvals issued
5.Loans submitted
6.Loans approved
7.Loans closed and funded
Identify where opportunities are slowing down.
Are borrowers failing to complete applications? Are documentation issues delaying underwriting? Are referral partners sending leads that don't match your lending capabilities?
Understanding your conversion metrics can help you improve productivity without simply increasing your prospecting volume.
9. Strengthen Your Operational Relationships
A strong loan officer understands that closing loans is a team effort.
Build working relationships with:
·Loan processors
·Underwriters
·Account executives
·Closing coordinators
·Compliance personnel
·Brokerage leadership
Learn how to submit complete files, communicate expectations, and resolve problems early.
One of the most valuable qualities in a mortgage brokerage is the ability to get timely answers when a transaction becomes complicated.
Borrowers and referral partners remember the professionals who solve problems.
10. Create Your Next 90-Day Growth Plan
At the end of your first three months, review your progress and establish your next objectives.
Ask yourself:
·Which referral sources generated the strongest opportunities?
·Which loan programs attracted the most qualified borrowers?
·How many applications did I generate?
·What percentage of applications reached closing?
·Where did transactions experience delays?
·Which marketing activities produced meaningful conversations?
·What additional training would improve my performance?
Use those answers to build a business plan based on measurable activity and realistic production goals.
90-Day Milestone: Establish a repeatable business development system supported by clear performance metrics, strong operational relationships, and a growing pipeline.
Your First 90 Days: Sample Loan Officer Activity Scorecard
The following are illustrative activity targets—not production guarantees or industry benchmarks.
Activity | Days 1–30 | Days 31–60 | Days 61–90 |
Referral partner conversations | 15 | 25 | 30 |
Educational social posts | 8 | 12 | 12 |
Networking meetings | 4 | 6 | 8 |
Specialty program training sessions | 6 | 4 | 2 |
Pipeline reviews | Weekly | Weekly | Weekly |
Business development focus | Foundation | Prospecting | Conversion |
Adjust your targets based on your existing pipeline, market conditions, and business model.
The goal is to create consistency—not chase arbitrary numbers.
Why Mortgage Brokerage Platform Selection Matters
Not every mortgage brokerage provides the same resources.
When evaluating a new company, loan officers should look beyond compensation and consider the infrastructure supporting their business.
Important questions include:
Lender access: Does the brokerage offer financing solutions for a broad range of borrower scenarios?
Processing support: Will the operational structure help you deliver reliable service?
Technology: Does the company provide systems that simplify borrower communication and pipeline management?
Leadership: Can you access knowledgeable professionals when challenging situations arise?
Growth opportunities: Can you develop specialty lending niches or expand into commercial financing?
Business development: Does the company support the way you intend to build your mortgage business?
The best brokerage for one originator may not be the best fit for another.
The objective is to find a platform that supports your professional strengths and long-term business goals.
Why Consider Medallion Funds?
At Medallion Funds, our focus is helping mortgage professionals build sustainable businesses through lending options, technology, and operational support.
Our platform offers access to a range of residential and commercial mortgage solutions, including conventional financing, specialty residential lending, investment property financing, and commercial loan opportunities.
For originators interested in serving business owners and commercial real estate investors, our commercial lending relationships can provide additional opportunities to expand their expertise.
We believe that loan officers should be empowered to operate as knowledgeable financing advisors rather than simply quoting interest rates.
Whether you're an experienced loan officer considering a move or a mortgage professional exploring the brokerage model, the right environment can make a meaningful difference.
Frequently Asked Questions
How long does it take to become productive at a new mortgage brokerage?
The timeline varies based on licensing, existing referral relationships, pipeline transfers, product knowledge, and operational readiness. A structured 90-day plan can help establish productive habits, but it does not guarantee a particular funding timeline.
What should a loan officer do during the first 30 days?
Prioritize licensing and compliance, onboarding, product training, technology setup, and communication with your professional network.
Is moving from retail lending to mortgage brokerage difficult?
The transition can involve a learning curve, particularly when adapting to multiple wholesale lenders, different underwriting guidelines, and new technology. Strong training and operational support can help.
Can a mortgage broker offer more loan programs than a bank?
A mortgage broker may have access to multiple wholesale lenders and specialty programs, while a bank may primarily offer its own products. Actual options depend on the brokerage's lender relationships, licensing, and program availability.
Should new mortgage brokers specialize in a particular niche?
Specialization can improve marketing clarity and referral partner positioning. Doctors, dentists, self-employed borrowers, veterans, and real estate investors are examples of potentially valuable niches.
How should loan officers measure success during their first 90 days?
Track referral conversations, applications, qualified pipeline volume, conversion rates, closing performance, and business development activity—not just funded volume.
Final Thoughts: Your First 90 Days Can Shape Your Next Three Years
Joining a new mortgage brokerage represents an opportunity to rethink how you build your business.
But success requires more than a new logo, compensation agreement, or lender list.
It requires disciplined execution.
Days 1–30: Learn the platform and build your foundation.
Days 31–60: Reconnect, prospect, and generate opportunities.
Days 61–90: Improve conversion, strengthen operations, and build momentum.
The most successful transition is one that positions you to serve borrowers more effectively while developing a repeatable business model.
Ready to Explore a New Mortgage Brokerage Opportunity?
If you're considering changing mortgage companies and want to learn more about the opportunities available through Medallion Funds, let's have a conversation.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302Las Vegas, NV 89141
Texas Complaint and Recovery Fund Notice
All Rights Reserved Copyright © 2021 - Bill Rapp The Mortgage Viking | NMLS #228246