ATTENTION: For Those who are serious about Getting Pre-Qualified FAST!
Bill Rapp, Mortgage Originator: NMLS 228246
"Brokers Are Better.
Better Pricing, Better Service!"
Subscribe To My List Below To Get Your Mortgage Quote Now!
Simply enter your name and email below:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
FHA 203 H Loan Product
The Section 203(h) program allows the Federal Housing Administration (FHA) to insure mortgages made by qualified lenders to victims of a major disaster who have lost their homes and are in the process of rebuilding or buying another home.
Purpose:
Through Section 203(h), the Federal Government helps victims in Presidentially designated disaster areas recover by making it easier for them to get mortgages and become homeowners or re-establish themselves as homeowners.
Type of Assistance:
This program provides mortgage insurance to protect lenders against the risk of default on mortgages to qualified disaster victims. Individuals are eligible for this program if their homes are located in an area that was designated by the President as a disaster area and if their homes were destroyed or damaged to such an extent that reconstruction or replacement is necessary. Insured mortgages may be used to finance the purchase or reconstruction of a one-family home that will be the principal residence of the homeowner. Like the basic FHA mortgage insurance program it resembles (Section 203(b) Mortgage Insurance for One to Four Family Homes), Section 203(h) offers features that make recovery from a disaster easier for homeowners:
No down payment is required. The borrower is eligible for 100 percent financing. Closing costs and prepaid expenses must be paid by the borrower in cash or paid through premium pricing or by the seller, subject to a 6 percent limitation on seller concessions.
FHA mortgage insurance is not free. Mortgagees collect from the borrowers an up-front insurance premium (which may be financed) at the time of purchase, as well as monthly premiums that are not financed, but instead are added to the regular mortgage payment.
HUD sets limits on the amount that may be insured. To make sure that its programs serve low and moderate income people, FHA sets limits on the dollar value of the mortgage. The current FHA mortgage limit can be viewed online. These figures vary over time and by place, depending on the cost of living and other factors (higher limits also exist for two to four family properties).
Eligible Customers:
Anyone whose home has been destroyed or severely damaged in a Presidentially declared disaster area is eligible to apply for mortgage insurance under this program.
Application:
The borrower's application for mortgage insurance must be submitted to the lender within one year of the President's declaration of the disaster. Applications are made through an FHA approved lending institution, who make their requests through a provision known as "Direct Endorsement," which authorizes them to consider applications without submitting paperwork to HUD. Mortgage insurance processing and administration for this and other FHA single family mortgage insurance products are handled through HUD's Homeownership Centers.
My best advice to you is to call Bill Rapp, the Mortgage Viking, to discuss your options today 281-222-0433.
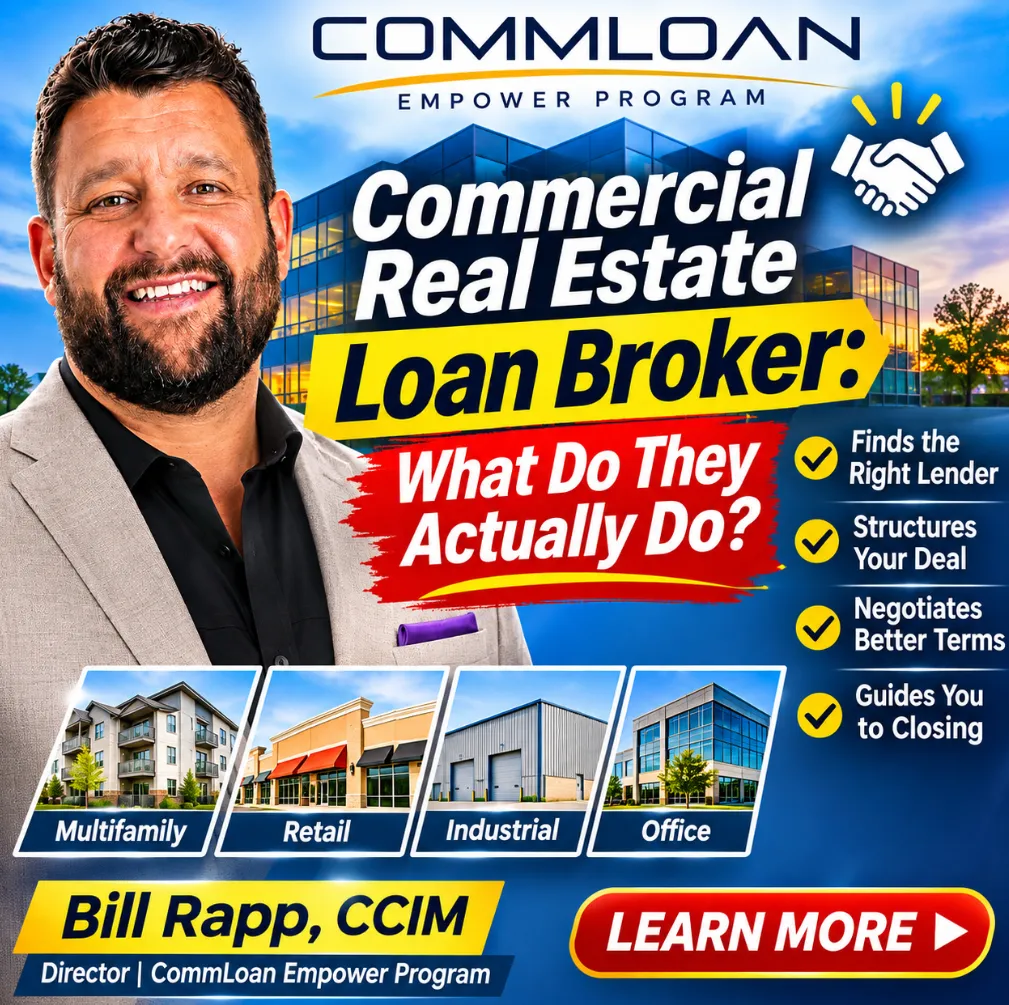
🏢 Commercial Real Estate Loan Broker: What Do They Do? 💰
🏢 Commercial Real Estate Loan Broker: What Do They Do? 💰
💼 What Does a Commercial Mortgage Broker Do? 🏦
_______________________________________________________________________________
Commercial Real Estate Loan Broker: What Does One Actually Do?
When you're purchasing a shopping center, refinancing an apartment complex, acquiring an industrial warehouse, or financing a building for your business, finding the right commercial real estate loan can be one of the most important decisions you'll make.
But here's something many investors and business owners don't realize:
The lender offering the lowest interest rate isn't necessarily offering the best financing solution.
Different commercial lenders evaluate properties, borrowers, cash flow, and risk differently. A loan that works perfectly for one lender might be rejected by another.
That's where a commercial real estate loan broker comes in.
A qualified commercial mortgage broker does more than submit loan applications. They help borrowers evaluate financing options, identify appropriate capital sources, structure transactions, negotiate terms, and navigate the commercial loan process.
Let's explore what commercial real estate loan brokers actually do, how they get paid, and when hiring one makes financial sense.
What Is a Commercial Real Estate Loan Broker?
A commercial real estate loan broker is a financing intermediary who connects commercial property investors and business owners with lenders offering financing for commercial real estate transactions.
Unlike a bank loan officer, who generally originates loans through their institution's available programs, an independent commercial mortgage broker may work with multiple capital providers.
These providers can include:
Commercial banks and credit unions
SBA 7(a) and SBA 504 lenders
Commercial mortgage-backed securities (CMBS) lenders
Fannie Mae and Freddie Mac multifamily lenders
Life insurance companies
Debt funds and private credit providers
Bridge and transitional lenders
Construction lenders
Specialty commercial finance companies
The objective isn't simply to find a lender willing to approve a loan.
It's to identify financing that aligns with the property's performance, the borrower's financial position, and the investor's long-term strategy.
1. A Commercial Loan Broker Evaluates Your Financing Needs
Before approaching lenders, an experienced commercial real estate loan broker should understand the transaction.
That starts with evaluating the property, borrower, and proposed financing structure.
Important considerations include:
Property type: Is the asset multifamily, retail, office, industrial, hospitality, self-storage, or another commercial property type?
Loan purpose: Are you purchasing, refinancing, renovating, developing, or accessing equity?
Property performance: What are the occupancy, rental income, operating expenses, and net operating income?
Borrower qualifications: What are the borrower's liquidity, credit history, experience, and financial strength?
Investment strategy: Are you planning to hold the property long-term, renovate and reposition it, or sell within several years?
For example, an investor purchasing a stabilized apartment building may benefit from a different financing structure than an investor acquiring a partially vacant retail center.
The right commercial mortgage broker understands these distinctions before presenting the transaction to lenders.
2. A Commercial Mortgage Broker Identifies Appropriate Lenders
One of the biggest challenges in commercial real estate financing is that lenders don't all operate under the same underwriting guidelines.
A traditional bank may prefer stabilized properties, strong borrowers, and conservative leverage.
A bridge lender may consider a property with significant vacancy if the borrower has a credible improvement strategy.
An SBA lender may finance an eligible owner-occupied commercial building that doesn't fit a conventional investment-property loan program.
A multifamily agency lender may offer attractive long-term financing for a qualifying apartment property.
The same property can receive dramatically different financing proposals depending on which lenders review the transaction.
An experienced broker helps borrowers avoid approaching lenders whose programs don't match their needs.
How CommLoan Helps Match Borrowers With Capital Sources
Through CommLoan's CUPID™ commercial lending technology, borrowers can be matched with potential financing programs based on their transaction characteristics.
Rather than relying exclusively on one bank's lending criteria, the platform supports a broader lender-matching and comparison process.
The objective is to identify relevant financing alternatives more efficiently and help borrowers make informed decisions.
Lender matches are potential options, not loan approvals or commitments.
3. A Commercial Real Estate Loan Broker Helps Structure the Loan
Commercial financing involves much more than choosing an interest rate.
An experienced commercial loan broker evaluates the entire loan structure.
Loan-to-Value Ratio (LTV)
LTV measures the loan amount relative to the property's appraised value.
For example:
Property value: $3,000,000
Proposed loan: $2,100,000
LTV: 70%
A lender may advertise 70% LTV financing, but that doesn't mean every qualifying property will receive that leverage.
Other underwriting requirements may limit the loan amount.
Debt Service Coverage Ratio (DSCR)
DSCR measures a property's ability to cover required debt payments from net operating income.
DSCR = Net Operating Income ÷ Annual Debt Service
Suppose a property generates $240,000 in annual NOI and has $180,000 in annual debt service.
DSCR = $240,000 ÷ $180,000 = 1.33x
That means the property generates approximately $1.33 in NOI for every $1.00 of required annual debt service.
Lenders establish different minimum DSCR requirements based on their programs and risk assessment.
Amortization and Loan Term
A commercial loan might have a five-year term with payments calculated using a 25-year amortization schedule.
Another lender might offer a 10-year term with 30-year amortization.
These differences affect monthly cash flow, balloon-payment exposure, and refinancing risk.
Recourse vs. Nonrecourse
Recourse financing generally allows the lender to pursue certain borrower or guarantor assets if the loan defaults, subject to applicable documents and law.
Nonrecourse financing generally limits recovery to specified collateral, although customary carveouts can create personal liability under certain circumstances.
Understanding these provisions is critical when evaluating commercial mortgage proposals.
4. A Commercial Loan Broker Compares Financing Proposals
A lower interest rate doesn't automatically mean a better commercial mortgage.
Consider two hypothetical financing options:
Loan Feature | Lender A | Lender B |
Loan amount | $2,000,000 | $2,000,000 |
Interest rate | 6.75% | 7.00% |
Amortization | 20 years | 30 years |
Loan term | 5 years | 10 years |
Prepayment terms | To be negotiated | To be negotiated |
Recourse | To be determined | To be determined |
Although Lender A has a lower interest rate, Lender B's longer amortization may provide lower monthly principal-and-interest payments.
However, Lender B may also result in slower principal repayment and higher interest expense over comparable periods.
A qualified broker evaluates the tradeoffs, including:
Monthly debt service
Total financing costs
Origination and lender fees
Prepayment penalties
Cash-flow flexibility
Recourse provisions
Required reserves
Closing timelines
Balloon-payment and refinancing exposure
The best loan depends on the borrower's objectives—not simply the advertised rate.
5. A Commercial Mortgage Broker Coordinates Underwriting and Closing
Once a financing option is selected, the work isn't finished.
Commercial mortgage transactions often require substantial documentation.
Common lender requests include:
Current rent roll
Historical operating statements
Trailing 12-month income and expenses
Business and personal tax returns
Personal financial statement
Schedule of real estate owned
Existing loan information
Entity formation documents
Property insurance information
Leases and tenant information
Appraisal, environmental, and property condition reports
A commercial loan broker helps organize these materials, communicate with the lender, address underwriting questions, and coordinate with the relevant transaction professionals.
Depending on the deal, those professionals may include the real estate broker, title company, attorney, appraiser, environmental consultant, insurance agent, and lender's closing team.
A good broker helps identify potential problems early rather than waiting until closing.
Real-World Example: Financing a $3 Million Shopping Center
Imagine an investor purchasing a neighborhood shopping center for $3 million.
The property generates $210,000 in annual net operating income.
The investor wants a $2.1 million loan, representing 70% LTV.
At first glance, that may seem reasonable.
But suppose the lender requires a minimum DSCR of 1.25x.
The maximum annual debt service supported by the property's NOI would be:
$210,000 ÷ 1.25 = $168,000 annually
Now assume a proposed 7% interest rate with 25-year amortization.
The annual principal-and-interest payments on a $2.1 million loan would be approximately $178,000.
That produces a DSCR of approximately 1.18x.
The property may meet the lender's LTV guideline while failing its DSCR requirement.
A commercial real estate loan broker could evaluate several alternatives:
1.Reduce the requested loan amount.
2.Compare lenders with different underwriting requirements.
3.Evaluate longer amortization where available.
4.Explore whether documented additional income or legitimate expense adjustments improve underwritten NOI.
5.Consider bridge financing if the property has a credible stabilization strategy.
The goal isn't to force a deal through underwriting.
It's to identify a responsible financing structure supported by the property's economics.
6. How Much Does a Commercial Real Estate Loan Broker Charge?
Commercial mortgage broker compensation varies based on the loan type, transaction size, complexity, and financing arrangement.
Some brokers receive a lender-paid fee, while others charge a borrower-paid origination or brokerage fee.
For illustration, a 1% brokerage fee on a $2 million commercial loan would equal $20,000.
However, that is only an example—not a universal fee schedule.
Borrowers should ask:
What brokerage or origination fees apply?
Who pays those fees?
Are there additional lender or third-party costs?
Is any fee due before closing?
Is the broker compensated differently depending on the lender selected?
Are any fees refundable?
Compensation and disclosure requirements depend on the transaction and applicable law.
Always request a clear written explanation of compensation before proceeding.
7. When Should You Hire a Commercial Real Estate Loan Broker?
Working with a commercial mortgage broker may be particularly valuable when:
You're purchasing commercial property. A broker can help compare financing structures before your purchase contract deadlines become critical.
You're refinancing an existing loan. A broker can assess maturity risk, cash flow, valuation, and replacement financing options.
Your bank declined the transaction. A broker may identify other lenders with different risk appetites, although alternative financing isn't guaranteed.
You're financing a specialized property. Hotels, churches, self-storage facilities, and certain owner-user properties may require specialized lenders.
You're acquiring a value-add property. Bridge or transitional financing may be more appropriate than permanent financing during stabilization.
You're a business owner buying your building. SBA and conventional owner-occupied financing options may offer different structures, eligibility rules, and equity requirements.
The earlier you evaluate financing, the more time you generally have to address potential obstacles.
8. How to Choose the Right Commercial Mortgage Broker
Not every commercial loan broker offers the same experience, lender access, or advisory capabilities.
Before choosing a broker, consider asking:
1.What commercial property types do you regularly finance?
2.Which lender categories can you access?
3.How do you evaluate DSCR, LTV, and borrower qualifications?
4.Can you compare multiple financing structures?
5.How are you compensated?
6.What happens if the first lender declines the transaction?
7.Who manages communication during underwriting and closing?
Look for someone who can explain the financial implications of each option—not just quote an interest rate.
The Bottom Line: A Commercial Loan Broker Is a Capital Strategy Partner
Commercial real estate financing isn't one-size-fits-all.
Two investors purchasing similar properties can qualify for different financing based on their experience, liquidity, income, business plans, and lender selection.
A commercial real estate loan broker helps bridge the gap between a borrower's financing objectives and the requirements of potential capital providers.
The value comes from understanding the transaction, identifying appropriate lenders, evaluating financing structures, and helping navigate the process through closing.
Let's Find the Right Commercial Financing Strategy
I'm Bill Rapp, CCIM, Director with CommLoan, and I help commercial real estate investors and business owners evaluate financing strategies across a wide range of commercial property types.
Through the CommLoan Empower Program and CUPID™ lender-matching technology, we help borrowers explore commercial lending options without relying on a single lender's underwriting guidelines.
Whether you're purchasing, refinancing, developing, or expanding your commercial real estate portfolio, let's discuss your financing objectives.
Explore your commercial financing options:
https://billrapp.commloan.com/
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302Las Vegas, NV 89141
Texas Complaint and Recovery Fund Notice
All Rights Reserved Copyright © 2021 - Bill Rapp The Mortgage Viking | NMLS #228246