ATTENTION: For Those who are serious about Getting Pre-Qualified FAST!
Bill Rapp, Mortgage Originator: NMLS 228246
"Brokers Are Better.
Better Pricing, Better Service!"
Subscribe To My List Below To Get Your Mortgage Quote Now!
Simply enter your name and email below:
WITH PROVEN STRATEGIES & PROVEN RESULTS
HERE'S WHAT MY CLIENTS SAY:
What People Are Saying:
Excellent Service
Bill is an exceptional loan officer. He helped us to purchase our home with very personal and professional service. He helped us navigate the whole process from start to closing without any problems. We didn't think we're qualified to purchase a house, but Bill went above and beyond to find a way to help us achieve our goal. He always responded very quickly with our requests, he would come back with different options with comparison chart to clearly indicate how much we need for down payment, monthly payments, interest rates, closing costs etc.
We would highly recommend Bill to anyone in need of lending services. In fact, we have already recommended Bill to one of our friends on purchasing a house.
--- David Chan - Houston, TX
Bank Statement Lending!
William Rapp of Network Funding, L. P. was very professional and I felt comfortable in dealing with him. I will definitely recommend him to family and friends.
--- Ian F - Missouri City, TX
Professionalism - Expert In Home Style Loan
Bill is an expert in the topic, his explanations and online material make a difference and he is always there from the beginning to the end. He is committed to make thing happen.
--- Felipe Caldern & Carolina Angel Gutierrez
Great Service!
Bill Rapp's handling of our loan (even though out of state) was unparalleled to any service I have been through prior, including 3 different real estate transactions and multiple refinances. Extremely quick close, with great options and flexibility for my families needs. All around A+
--- Chris & Beth Sheehan - San Jose, CA
Knowledgeable and Responsive!
Bill was a pleasure to work with and he made the loan process fairly easy. He answered all questions I had very quickly and was straight forward in doing it. I would recommend Bill to others.
--- Wes Brady - Richmond, TX
Very professional and always returned our calls!
Bill takes a lot of pride in his job and is very dependable. They were very patient and understanding. He went out of his way and explained all my questions and concerns. They were very professional and returned my phone calls and emails. He did a great job and I fully recommend him.
--- Therese, Malcom & Shirley Teixeira - Katy, TX
Great Job!
Bill helped us out from beginning to end of loan process. The loan closed in a timely manner as Bill worked hard with bank to get our to the final steps.
--- Kamal & Theresa Wilson - Hartford, CT
Avid Problem-Solver and Absolute Pleasure to Work With!
Bill Rapp worked very hard to ensure that we closed our loan and were able to move into our new home. He always had alternatives to any problems we encountered while closing. He worked with us from the beginning identifying solutions to any problems that we were having. He was an absolute pleasure to work with!
--- Nikita Rayani & Sanit Tejani - Houston, TX
Awesome to work with!
Being a first-time buyer I came in with lots of questions and concerns. Bill was always available for any questions I had and answered everything to my satisfaction. Bill made the loan process so painless that I could still concentrate on other things. We ended up closing early which made things even better. If you are in need of a lender and want someone who is very approachable and stays on top of your loan then Bill is your guy.
--- Cesar Raya - Richmond, TX
Loan Declined by my bank, and he saved the day!
Bill, did an amazing job helping me close on my house. He took the reigns and reassured me the best route to take to help close. He was accountable, thorough and trustworthy. I will continue to work with Network Funding, L.P. when it comes to home buying in the future because of the quality of service Bill gave.
--- Jacob Smith - Boerne, TX
Bill Rapp Will Definitely Make It Happen!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Corinne Wilson - Roselle, NJ
Knowledgeable, Honest, Trustworthy, and Reliable!
"I will definitely keep you in mind. If anyone I know needs financing, I will send them your way!"
--- Jon & Andrea Saleem, CRPC Financial Advisor - Houston, TX
Best Dam Mortgage Guy a man could know!
"Hands down the best loan experience to date!"
--- Gabe & Chelsea Jackson - Pearland, TX
Phenomenal, Hard Working and Never Quits!
Had a stupid foreclosure that could have been avoided if ex’s attny would have sent my buy out offer. So Bill was able to push this through with a 4 year foreclosure. He worked his butt off, was very diligent with his communication; and was very professional talking to me even when I was screaming and/or crying at him. Highly recommend this lender. He really go to the ends of the earth to help you!
--- Liz Keeter - Harlingen, TX
Exceptional customer service!
Bill is the most kind, patient and helpful person I have ever known. He answers his phone calls and emails promptly. You can ask him a million questions, and he will answer each and every one of them. Before I started working with Bill, I had been turned down for a home loan, because of some past credit issues I had, plus I was a single mother. However, once I started working with Bill, he was able to quickly get me a home loan, with a good interest rate. I would recommend that you call him, as he will help you.
--- Isha Lopez & Mauricio Garcia - Houston, TX
Service with a capitol S
Bill went above and beyond at every turn. He worked late on Saturday, he worked late all the time. We wanted to close ASAP and he really helped make it happen for us.
--- Jeff & Wendy Heger - Houston, TX
Best Buying Experience!
I would would highly recommend going with Network Funding LP. As a first time home buyer I didn't know what to expect. Bill Rapp was very helpful in answering all my questions and guided me through all ghe steps. I couldn't have asked for a better buying experience!
--- Tabitha Turner - Humble, TX
Would recommend him and use him again!
Very involved and professional . Kept me informed and up to date on everything that was going on Went with me closing and was very helpful and knowledgeable.
--- Kathy Ward - Houston, TX
Great experience!
Well I meet bill back in December 2016 he got recommended by my real estate agent we had a house in sight and started the process to get approved but we fail due to my work history and credit bill told me not to give up and put me in contact with a credit repair company they help me bring my score up and bill walk me thru the process of getting a new line so this time around we got approved before looking for our house after we found it we still had a couple of hick up but with bills help on Sunday 6-18-17 to be exact Father's Day bill called me to give me the great news that we had got approved and the closing date was as scheduled bill was more than just a lender to my family he became a friend and I'm alway going to have him in mind for any other financial situation.
--- Alejandres Felimon - Richmond, TX
I really liked his attitude!
I wouldn't usually say this but the way he had handled my mortgage was really pleasant. I personally enjoyed the time spent with him while we discussed feasible rates. He's a great man with a great personality and he offered really low interests as well. Definitely recommend him to others.
--- Tom Troiano - Atlantic City, NJ
He's nothing short of a miracle!
I'm a self-employed businessman and had him figure out the mortgage of the house after 30% down payment. The interest rates I received were incredibly low given what I had thought of earlier. One other important thing to note was that I hadn't really taken any loans earlier, so I had no credit history. He helped me out with all that as well so I can't really call him anything else but a miracle.
--- Fran Suarez - Cleveland, OH
He's really helpful!
I made a bid to him and the very same day he gave me an offer which I couldn't resist. It was too intimidating with those incredibly low interest rates and all, thoroughly recommend him.
--- Kenny Mickle - Houston, TX
Expeditious!
Bill was very expeditious and made it real easy going through the loan process. I felt he was on top of things.
I deal with investment properties and will more than likely call on him again.
--- Wayne King - Pensacola, FL
Bill was great!
Bill made us feel like a friend all the way thru the process. He was patient and explained everything he needed clearly. He was available ANYTIME we had questions or needed more information. Hopefully we won’t go thru this process again anytime soon, but if we do - we’d choose Bill! =)
--- Barbra & Nick Grimmer - Austin, TX
Great broker!
Bill was a great broker to work with. As first time home buyers we had many questions about the process, Bill took the time to help us even calling us back on weekends with answers. I would not hesitate to recommend him to anyone looking for a broker to work with.
--- Murray & Lisa Turner - Pensacola, FL
Outstanding service!
I couldn't have been more pleased with Bill's level of service. He made what is typically a lengthy, arduous process far quicker and easier at every turn. I'm extremely comfortable recommending Bill to friends and family, and will definitely utilize his services again!
--- Jim Lipari - Austin, TX
FHA 203 H Loan Product
The Section 203(h) program allows the Federal Housing Administration (FHA) to insure mortgages made by qualified lenders to victims of a major disaster who have lost their homes and are in the process of rebuilding or buying another home.
Purpose:
Through Section 203(h), the Federal Government helps victims in Presidentially designated disaster areas recover by making it easier for them to get mortgages and become homeowners or re-establish themselves as homeowners.
Type of Assistance:
This program provides mortgage insurance to protect lenders against the risk of default on mortgages to qualified disaster victims. Individuals are eligible for this program if their homes are located in an area that was designated by the President as a disaster area and if their homes were destroyed or damaged to such an extent that reconstruction or replacement is necessary. Insured mortgages may be used to finance the purchase or reconstruction of a one-family home that will be the principal residence of the homeowner. Like the basic FHA mortgage insurance program it resembles (Section 203(b) Mortgage Insurance for One to Four Family Homes), Section 203(h) offers features that make recovery from a disaster easier for homeowners:
No down payment is required. The borrower is eligible for 100 percent financing. Closing costs and prepaid expenses must be paid by the borrower in cash or paid through premium pricing or by the seller, subject to a 6 percent limitation on seller concessions.
FHA mortgage insurance is not free. Mortgagees collect from the borrowers an up-front insurance premium (which may be financed) at the time of purchase, as well as monthly premiums that are not financed, but instead are added to the regular mortgage payment.
HUD sets limits on the amount that may be insured. To make sure that its programs serve low and moderate income people, FHA sets limits on the dollar value of the mortgage. The current FHA mortgage limit can be viewed online. These figures vary over time and by place, depending on the cost of living and other factors (higher limits also exist for two to four family properties).
Eligible Customers:
Anyone whose home has been destroyed or severely damaged in a Presidentially declared disaster area is eligible to apply for mortgage insurance under this program.
Application:
The borrower's application for mortgage insurance must be submitted to the lender within one year of the President's declaration of the disaster. Applications are made through an FHA approved lending institution, who make their requests through a provision known as "Direct Endorsement," which authorizes them to consider applications without submitting paperwork to HUD. Mortgage insurance processing and administration for this and other FHA single family mortgage insurance products are handled through HUD's Homeownership Centers.
My best advice to you is to call Bill Rapp, the Mortgage Viking, to discuss your options today 281-222-0433.
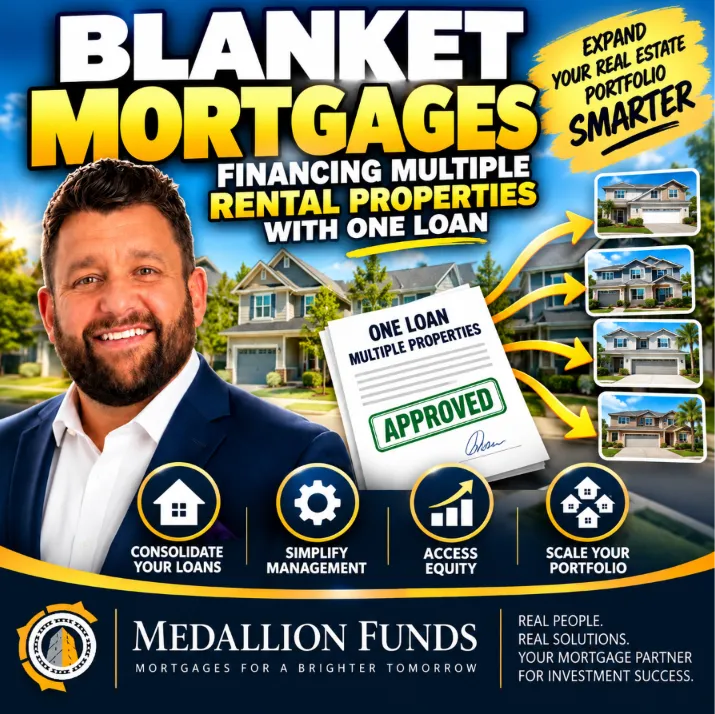
🏘️ Blanket Mortgages Explained: How to Finance Multiple Rental Properties With One Loan 💰
🏘️ Blanket Mortgages Explained: How to Finance Multiple Rental Properties With One Loan 💰
🚀 One Loan, Multiple Rental Properties: How Blanket Mortgages Help Real Estate Investors Scale 🏡
___________________________________________________________
🏘️ Blanket Mortgages: How to Finance Multiple Rental Properties With One Loan
Managing multiple rental properties can be an excellent way to build long-term wealth. However, as your investment portfolio grows, managing separate mortgages, payment schedules, loan maturities, and refinancing requirements can become increasingly complicated.
What if you could finance several investment properties under one mortgage?
That's exactly what a blanket mortgage may allow you to do.
For experienced real estate investors, blanket mortgage loans can offer a way to consolidate financing, simplify portfolio management, and potentially access capital for additional acquisitions.
But these loans aren't right for every investor.
At Medallion Funds, we help investors evaluate financing strategies based on their rental property portfolios, cash flow, equity positions, and long-term investment objectives.
Here's what you need to know.
What Is a Blanket Mortgage?
A blanket mortgage is a single loan secured by two or more real estate properties.
Instead of obtaining individual mortgages for each investment property, a borrower may finance several properties through one loan agreement.
For example, imagine an investor owns five single-family rental homes.
Rather than managing five separate mortgages, the investor might refinance those properties into one blanket mortgage secured by all five homes.
The properties remain separate real estate assets, but they collectively secure the financing.
Important distinction: A blanket mortgage is not simply five loans combined into one payment. It is a financing structure in which multiple properties serve as collateral for one debt obligation.
Example: Financing Five Rental Properties
Combined property value
$1,500,000
Illustrative LTV
70%
Potential loan amount
$1,050,000
Portfolio equity
$450,000
Illustrative financing structure only. Actual proceeds depend on underwriting, existing liens, property eligibility, cash flow, and lender requirements.
How Do Blanket Mortgage Loans Work?
A blanket mortgage lender evaluates the portfolio as a whole, while also reviewing the individual properties.
Underwriting may include:
Combined property values and loan-to-value ratio (LTV)
Rental income and operating expenses
Debt service coverage ratio (DSCR)
Property locations, conditions, and occupancy
Borrower liquidity, credit, and real estate experience
Ownership structure and existing mortgages
The requested loan term and repayment strategy
Some programs emphasize portfolio cash flow, while others also rely heavily on borrower financial strength.
Lenders may offer blanket mortgages for stabilized rental portfolios, acquisition financing, refinancing, or portfolio restructuring.
Five Potential Benefits of Blanket Mortgages
1. Simplified Mortgage Management
One blanket mortgage can replace several individual loans.
That may mean fewer payment schedules, loan statements, and maturity dates to monitor.
For investors managing multiple properties, streamlined financing can reduce administrative complexity.
2. Potential Financing Flexibility
A portfolio with significant equity and strong rental income may provide opportunities to restructure existing debt.
Depending on lender guidelines, investors may be able to refinance multiple properties together or access available equity.
However, combining properties does not automatically increase borrowing capacity.
3. Portfolio Expansion Opportunities
Some blanket loan structures can accommodate additional properties, subject to lender approval and loan terms.
This may benefit investors purchasing several rental properties at once or building a larger portfolio over time.
4. Potential Transaction Efficiencies
Financing several properties together may reduce some duplicated administrative or loan-processing expenses.
However, appraisal fees, title work, legal expenses, recording charges, and other costs may still apply to individual properties.
Investors should compare total financing costs rather than assume one loan will always be cheaper.
5. Flexible Property Release Provisions
One particularly valuable feature of certain blanket mortgage programs is a partial release clause.
This provision may allow the borrower to sell one property and release it from the blanket mortgage without paying off the entire loan.
The lender typically requires a specified principal reduction, sometimes called a release price, and may impose other conditions.
Not all blanket loans include partial release provisions.
Understanding the Partial Release Clause
Suppose an investor has five rental homes securing a $1 million blanket mortgage.
The investor decides to sell one property for $325,000.
If the loan includes a negotiated partial release provision, the lender may allow the property to be released after receiving an agreed principal payment.
For illustration, the lender might require a $250,000 principal reduction, leaving a $750,000 outstanding balance before other adjustments.
The investor could potentially retain the remaining sale proceeds after closing costs and other obligations.
Without an appropriate release provision, selling one property may require lender negotiations or a larger loan paydown.
Investor takeaway: Always understand the property release requirements before signing a blanket mortgage agreement.
Blanket Mortgage vs. Individual Rental Property Loans
Feature | Blanket Mortgage | Individual Mortgages |
|---|---|---|
Collateral | Multiple properties | Typically one property per loan |
Loan payments | Usually one | Multiple |
Underwriting | Portfolio and property-level | Individual property and borrower |
Selling one property | May require partial release | Generally pay off that property's loan |
Financing flexibility | Depends on portfolio loan terms | Each loan can be managed independently |
Cross-collateral risk | Generally higher | Generally isolated by loan |
The right structure depends on how frequently the investor plans to acquire, refinance, or sell properties.
Blanket Mortgage vs. DSCR Loans
Real estate investors often ask whether they should use a blanket mortgage or individual DSCR loans.
A DSCR loan generally emphasizes the rental property's ability to generate sufficient income to support debt payments.
A blanket mortgage describes the collateral structure, not necessarily the underwriting method.
In fact, some blanket mortgage programs use DSCR-based underwriting.
An investor with three rental homes might benefit from individual DSCR loans if the properties will be sold separately.
Another investor holding 15 stabilized rentals for the long term may prefer portfolio financing.
Neither approach is universally better.
How Much Down Payment or Equity Is Required?
Down payment and equity requirements vary by lender, property type, portfolio characteristics, and borrower qualifications.
For illustration, a lender offering 70% LTV on a $2 million eligible portfolio could potentially provide $1.4 million in financing.
That leaves $600,000 in equity.
However, LTV is only one component of underwriting. Rental cash flow, DSCR, borrower liquidity, and other constraints may reduce the available loan amount.
Investors should also account for closing costs and required reserves.
Who Should Consider a Blanket Mortgage?
Blanket mortgages may be particularly useful for:
Investors owning multiple single-family rental properties
Landlords managing several duplexes, triplexes, or fourplexes
Investors acquiring rental property portfolios
LLCs holding multiple investment properties
Buy-and-hold investors seeking consolidated financing
Experienced investors refinancing several properties simultaneously
They may be less appropriate for investors who frequently sell individual properties, prefer separate financing for each asset, or cannot obtain acceptable release terms.
What Are the Risks of Blanket Mortgages?
Although blanket mortgages offer potential advantages, investors should carefully consider the trade-offs.
Cross-collateralization: Multiple properties secure the same debt. A default may expose more than one property to lender remedies.
Refinancing risk: If a loan has a balloon maturity, the investor may need to refinance or repay the remaining balance when it comes due.
Partial release restrictions: Selling one property may require lender approval and a substantial principal paydown.
Portfolio concentration: Weak performance at several properties can affect the financing of the entire portfolio.
Loan terms: Some portfolio products may have prepayment penalties, minimum loan sizes, recourse provisions, or higher financing costs.
Investors should evaluate the complete loan agreement, not just the interest rate.
How to Qualify for a Blanket Mortgage
While requirements vary, lenders commonly request:
A current property schedule identifying each asset, address, value, and outstanding debt.
Rent rolls and current lease information.
Property-level income and expense statements.
Mortgage statements and insurance information.
Entity documents, if the properties are held in an LLC.
Borrower financial information, liquidity documentation, and investment experience.
A clear explanation of the requested financing and exit strategy.
A complete portfolio package helps lenders assess collateral quality, cash flow, and overall risk.
Frequently Asked Questions
Can I combine several rental properties into one mortgage?
Potentially, yes. Eligible properties may be refinanced under a blanket mortgage, subject to lender requirements, lien payoffs, ownership considerations, and underwriting approval.
Can I get a blanket mortgage with an LLC?
Yes, many portfolio lending programs permit eligible LLC borrowers. Lenders may still require personal guarantees or additional documentation.
How many properties do I need for a blanket mortgage?
Generally, at least two properties. Some lenders require more properties or a minimum combined loan amount.
Can I sell one property without refinancing the entire loan?
Possibly. This depends on the partial release provisions and the lender's approval requirements.
Are blanket mortgages available for properties in different states?
Some lenders permit geographically diversified portfolios, while others limit eligible states or markets.
Are blanket mortgage interest rates higher?
Not necessarily. Pricing depends on the lender, collateral, leverage, DSCR, loan term, borrower strength, and market conditions.
Can I use a blanket mortgage to purchase multiple rental properties?
Yes, some programs allow investors to acquire multiple properties through one financing arrangement, subject to program guidelines.
Final Thoughts: Is a Blanket Mortgage Right for Your Rental Portfolio?
A blanket mortgage can be a valuable financing tool for real estate investors who own multiple properties and want a more coordinated approach to managing their debt.
But convenience alone should never determine the financing decision.
The most important considerations include borrowing costs, cash flow, equity, property release flexibility, cross-collateralization, and long-term investment strategy.
At Medallion Funds, we help investors compare financing structures so they can evaluate what works best for their portfolios.
Ready to explore financing for multiple rental properties?
Contact Bill Rapp, CCIM, Director of Capital Advisory at Medallion Funds, to discuss your investment portfolio and available financing strategies.
Bill Rapp, CCIM
Director of Capital Advisory | Medallion Funds
NMLS #228246
Residential mortgage availability depends on applicable state licensing; commercial and investor programs depend on lender eligibility and property location.
MedallionFunds.com | Schedule a Consultation
Educational information only. This is not a commitment to lend or an offer of specific financing terms. All loans are subject to underwriting, program availability, and approval.
Main Office:
Medallion Funds
[email protected]
11920 Southern Highlands PKWY Suite 302Las Vegas, NV 89141
Texas Complaint and Recovery Fund Notice
All Rights Reserved Copyright © 2021 - Bill Rapp The Mortgage Viking | NMLS #228246